Summer Landscape of Asian Energy Markets: A New Paradigm in Energy Spot Prices Amid Intertwined Factors
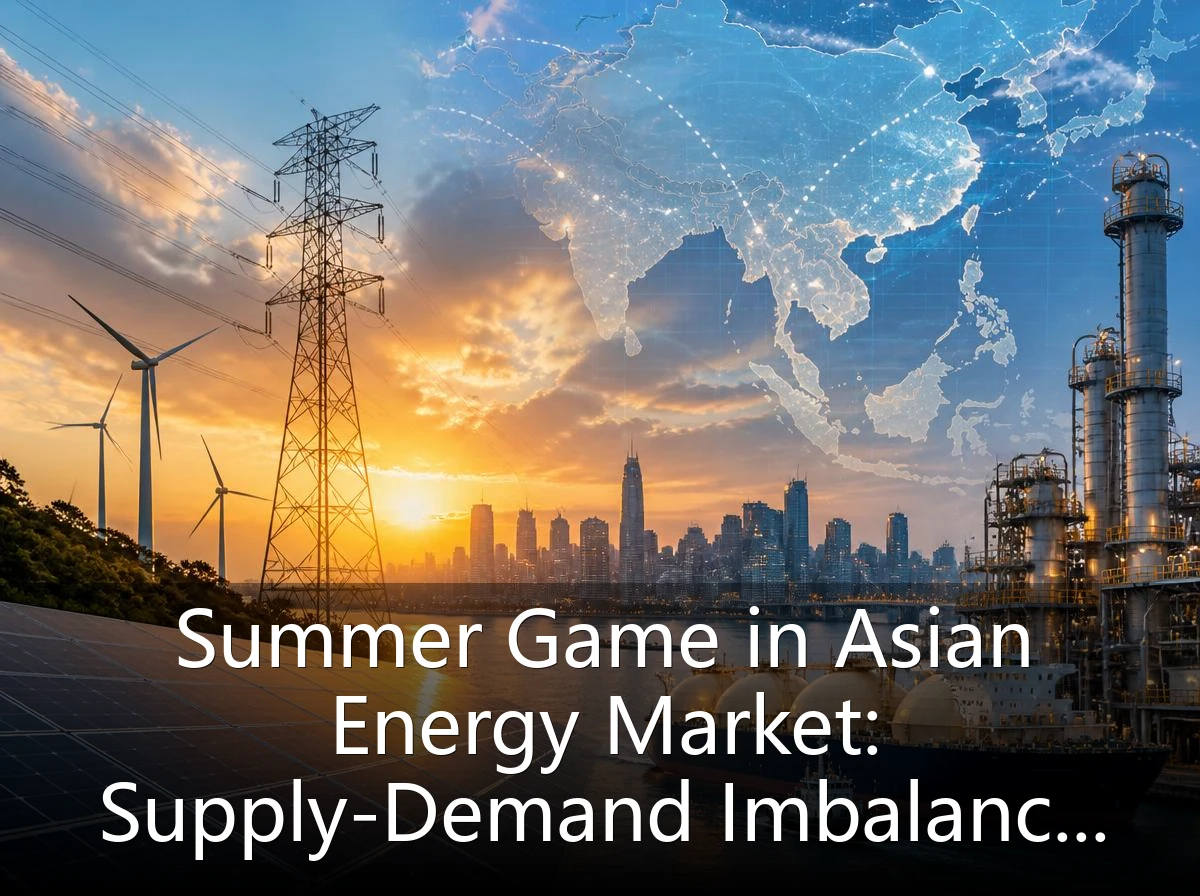
In the summer of 2026, the Asian energy market presents a complex and volatile situation, with multiple factors collectively reshaping the energy spot price structure. As the world's largest energy consumption region, the dynamics of the Asian energy market not only influence regional economic development but also have a profound impact on the global energy landscape. This article will deeply analyze the latest changes in the Asian energy market and the driving forces behind them from multiple dimensions, including supply and demand, geopolitics, and new energy development.
Latest Trends in the Asian Energy Market
Entering the summer of 2026, the Asian energy market exhibits a distinct polarization. On one hand, the prices of traditional energy sources such as oil and coal are experiencing increased volatility; on the other hand, new energies like wind, solar, and hydrogen are growing rapidly, leading to a profound transformation in the market structure.
According to the latest data, the energy consumption structure in Asia is undergoing accelerated transformation. The share of renewable energy in the power structure continues to increase, reaching 32% in the first half of 2026, a 5 percentage point increase from the same period last year. Concurrently, the growth rate of traditional energy consumption is slowing down, particularly the decline in coal consumption, which reflects the trend of Asian countries adjusting their energy policies toward low-carbon and clean energy.
Analysis of Summer Energy Price Trends
In the summer of 2026, Asian energy prices exhibit a "double-edged sword" pattern. Traditional energy prices are volatile, while the costs of new energies continue to decline, causing the price gap between the two to continuously narrow.
In the oil market, international oil prices experienced significant fluctuations during the summer of 2026. Influenced by multiple factors, including geopolitical tensions in the Middle East, global demand recovery, and OPEC+ production policies, Brent crude oil briefly surpassed $90 per barrel in early July, setting a new high for the year. However, prices subsequently fell to fluctuate around $85 per barrel due to demand concerns and a strengthening US dollar. Asia, as the world's largest oil-consuming market, has a significant impact on global oil prices through its demand changes.
In the natural gas market, Asian LNG spot prices showed an upward trend followed by a decline during the summer. In June, due to the surge in electricity demand caused by high temperatures in Asia and supply constraints from major exporting countries such as Australia and the United States, Asian LNG spot prices briefly exceeded $14 per million British thermal units, setting a new high for the year. However, with the cooling temperatures in late July and the release of new capacity, prices fell to around $12 per million British thermal units.
The coal market, on the other hand, showed a pattern of "not booming despite the peak season." Although summer is the peak electricity consumption period, the thermal coal prices were weak in the summer of 2026 due to strengthened coal consumption controls in major consuming countries like China and the increased share of new energy generation, with prices falling by about 8% from the beginning of the year and breaking the $100 per ton mark.
Changes in Supply and Demand
Supply and demand are the core factors determining energy prices. In the summer of 2026, the supply and demand structure of the Asian energy market underwent significant changes.
In terms of supply, traditional energy sources are showing diversification. Although the Middle East remains a core region for global oil supply, the production of non-OPEC countries such as the United States, Brazil, and Guyana continues to grow, leading to a more dispersed global oil supply structure. In the natural gas sector, the expansion of production from major exporters such as Australia, the United States, and Russia has significantly increased LNG supply capacity. In the coal sector, the increase in production from major exporting countries such as Indonesia and Russia has ensured sufficient global coal supply.
In terms of demand, the energy consumption structure in Asia is undergoing rapid transformation. On one hand, China's economic growth slowdown has led to a slowdown in energy consumption growth; on the other hand, emerging economies such as India and Southeast Asia are experiencing rapid energy consumption growth, becoming a major driving force for global energy demand. Concurrently, improvements in energy efficiency and industrial structure adjustments have led to a continuous decline in energy consumption per unit of GDP, weakening energy consumption intensity. What is particularly noteworthy is that Asian countries' energy policies are changing profoundly with the advancement of "dual carbon" goals. China has set targets of carbon peaking before 2030 and carbon neutrality before 2060, while India has committed to achieving carbon neutrality before 2070. These policy directions are reshaping Asia's energy consumption structure and exerting long-term restraint on traditional energy demand. Geopolitical Factors' Influence Geopolitics is a significant factor affecting the energy market. In the summer of 2026, the geopolitical situation in the Middle East was tense, and the safety of the Strait of Hormuz, a crucial channel for global oil transport, was under close scrutiny. Escalating tensions between Iran, the United States, and Israel led to increased market concerns about oil supply disruptions, which provided support to oil prices. The Russia-Ukraine conflict continues to have a profound impact on the European energy market, which is transmitted to Asian markets through energy trade chains. Europe's reduction in reliance on Russian energy and its shift to importing energy from the United States, the Middle East, and Africa have altered global energy trade flows, indirectly affecting the Asian energy market. Furthermore, geopolitical tensions within Asia are also impacting regional energy markets. Issues such as the South China Sea disputes and the Korean Peninsula situation could pose potential threats to energy transportation security, thereby influencing energy prices. The Impact of New Energy Development on Traditional Energy The rapid development of new energy is one of the most significant changes in the Asian energy market in recent years. In 2026, the installed capacity of renewable energy in the Asian region continued to grow, and costs continuously declined, putting increasing replacement pressure on traditional energy. In the solar energy sector, Asia continues to lead global development. Countries such as China, India, Japan, and South Korea are rapidly increasing their photovoltaic installed capacity. In the first half of 2026, the newly added capacity exceeded 50GW, accounting for over 60% of the global additions. The cost of photovoltaic power generation continues to decrease, achieving grid parity in many regions and forming strong competition for traditional electricity. In the wind energy sector, offshore wind power has become a new growth point. Asian countries such as China, Japan, and South Korea are densely implementing offshore wind projects, achieving a record high in newly added capacity in the first half of 2026. In particular, breakthroughs in floating wind power technology have made deep-sea wind energy resource development possible, further expanding the space for wind energy development. Hydrogen energy, as a representative clean energy, is seeing development opportunities in Asia. Countries such as Japan, South Korea, and China are formulating hydrogen energy development strategies, promoting the construction of green hydrogen production, storage, and application infrastructure. The gradual improvement of the hydrogen industry chain will have a profound impact on the traditional energy market. The rapid development of energy storage technology has solved the intermittency and volatility issues of new energy, improving the flexibility and stability of power systems. In the first half of 2026, the installed capacity of energy storage in the Asian region grew by over 40% year-on-year, providing technical support for the large-scale grid connection of new energy. How Investors Respond to Energy Market Fluctuations Faced with a complex and volatile energy market, investors need to adopt more flexible and diversified strategies to cope with fluctuations and risks. First, pay attention to policy direction. Energy policy is a crucial factor influencing the direction of the energy market. Investors need to closely monitor changes in energy policies of various countries, especially policy adjustments related to carbon neutrality and energy transition, to seize policy dividends and market opportunities. Second, emphasize technological innovation. The iteration speed of new energy technologies is fast, and technological innovation can lead to cost reduction and efficiency improvement, creating new investment opportunities. Investors should focus on enterprises and projects with core technological advantages. Third, strengthen risk management. The energy market has increased volatility, requiring investors to establish a comprehensive risk management system to reduce investment risks through diversification, hedging tools, and other means. Fourth, grasp regional differences. Asian countries have differences in energy resource endowments, development stages, and policy orientations. Investors need to formulate differentiated investment strategies based on the characteristics of different countries and regions. Future Outlook As for the future, the Asian energy market will exhibit the following development trends: First, the energy structure will continue to optimize. As the carbon neutrality process accelerates, the proportion of renewable energy in the energy structure will continuously increase, and the consumption proportion of traditional energy will gradually decrease. It is expected that by 2030, the share of renewable energy in the power structure in the Asian region will reach over 40%. Second, energy digitalization transformation is accelerating. Digital technologies such as smart grids, virtual power plants, and the energy internet will be widely applied in the energy sector, improving the efficiency and flexibility of the energy system and creating new business models and value growth points. Third, regional energy cooperation is deepening. Due to the uneven distribution of energy resources in Asia and the differences in the energy needs and development stages of various countries, strengthening regional energy cooperation and building an interconnected energy infrastructure network will be an important direction for Asian energy development. Fourth, energy and climate development are synergistic. Against the backdrop of climate change, energy development will advance in synergy with goals such as carbon emission reduction and ecological protection, making the energy system cleaner, lower carbon, and more efficient. Overall, the Asian energy market in the summer of 2026 is at a critical stage of transformation, with multiple factors intertwined, and the market landscape is undergoing profound changes. Investors need to grasp the major trend of energy transition, pay attention to technological innovation and policy direction, and find opportunities amidst volatility to achieve sustainable development.